Frequently Asked Questions
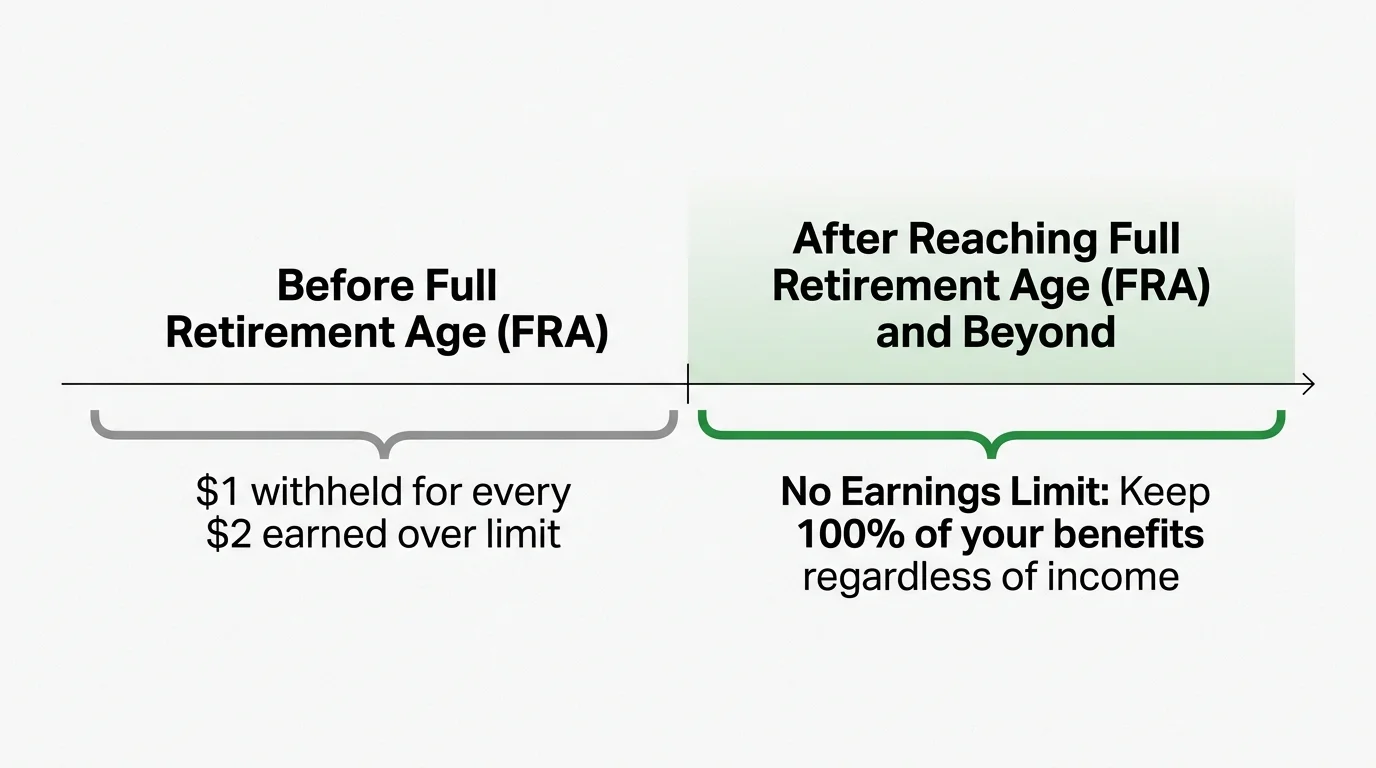
How does my continuing to work impact my benefits after I reach full retirement age?
Once you reach your precise full retirement age, the restrictive retirement earnings test disappears entirely. You can earn an unlimited amount of money from wages, corporate salary, or active self-employment without triggering any temporary reductions in your monthly Social Security check. Furthermore, your continued payroll tax contributions can actually increase your future payouts. The administration reviews your ongoing earnings record annually; if your current salary ranks among your 35 highest-earning years, they will automatically recalculate your primary insurance amount and issue a larger monthly check to perfectly reflect your updated, higher earning history.
Can I suspend my benefits if I change my mind after claiming?
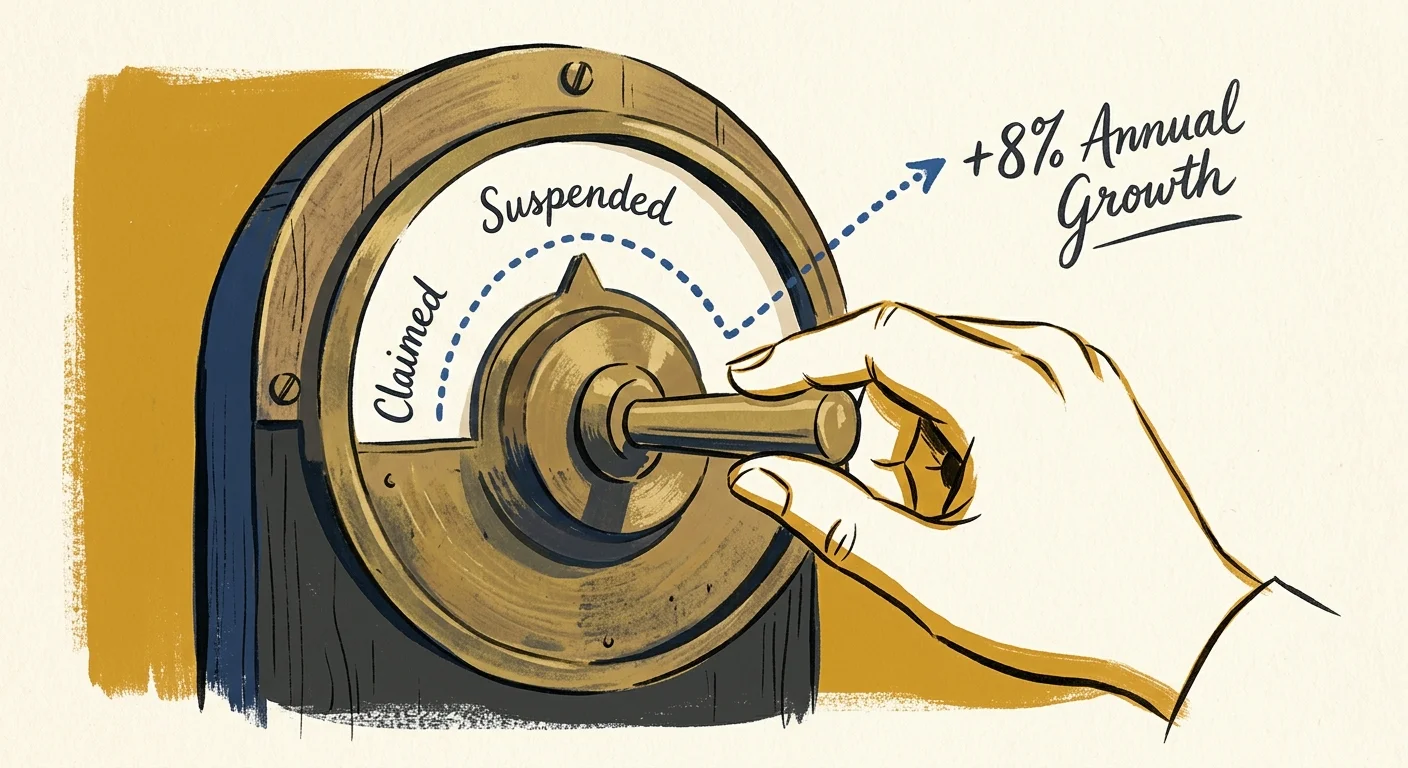
You possess a strict, one-time opportunity to completely undo your claiming decision if you actively file a formal withdrawal of application within 12 months of first receiving your benefits. To properly execute this withdrawal, you must repay every single dollar you and your family received based on your application, including withheld federal taxes and deducted Medicare premiums. If you miss this tight 12-month window but have reached your full retirement age, you can voluntarily choose to suspend your benefits. Suspending your ongoing payments allows you to earn delayed retirement credits—boosting your future payout by eight percent annually until age 70—without requiring you to repay the funds you already collected.
Will my Social Security benefits cover my long-term care expenses?
You should absolutely not rely on Social Security to fund any significant long-term care requirements. The average monthly benefit barely covers basic civilian living expenses and falls drastically short of the exorbitant, rapidly inflating costs associated with nursing homes, memory care assisted living facilities, or continuous in-home medical care. You must implement separate, highly focused retirement tips to adequately address these healthcare risks, such as purchasing dedicated long-term care insurance, funding a health savings account, or earmarking a specific portion of your investment portfolio to absorb catastrophic medical costs that Medicare and Social Security explicitly ignore.
How do international relocations affect my ability to collect federal retirement benefits?
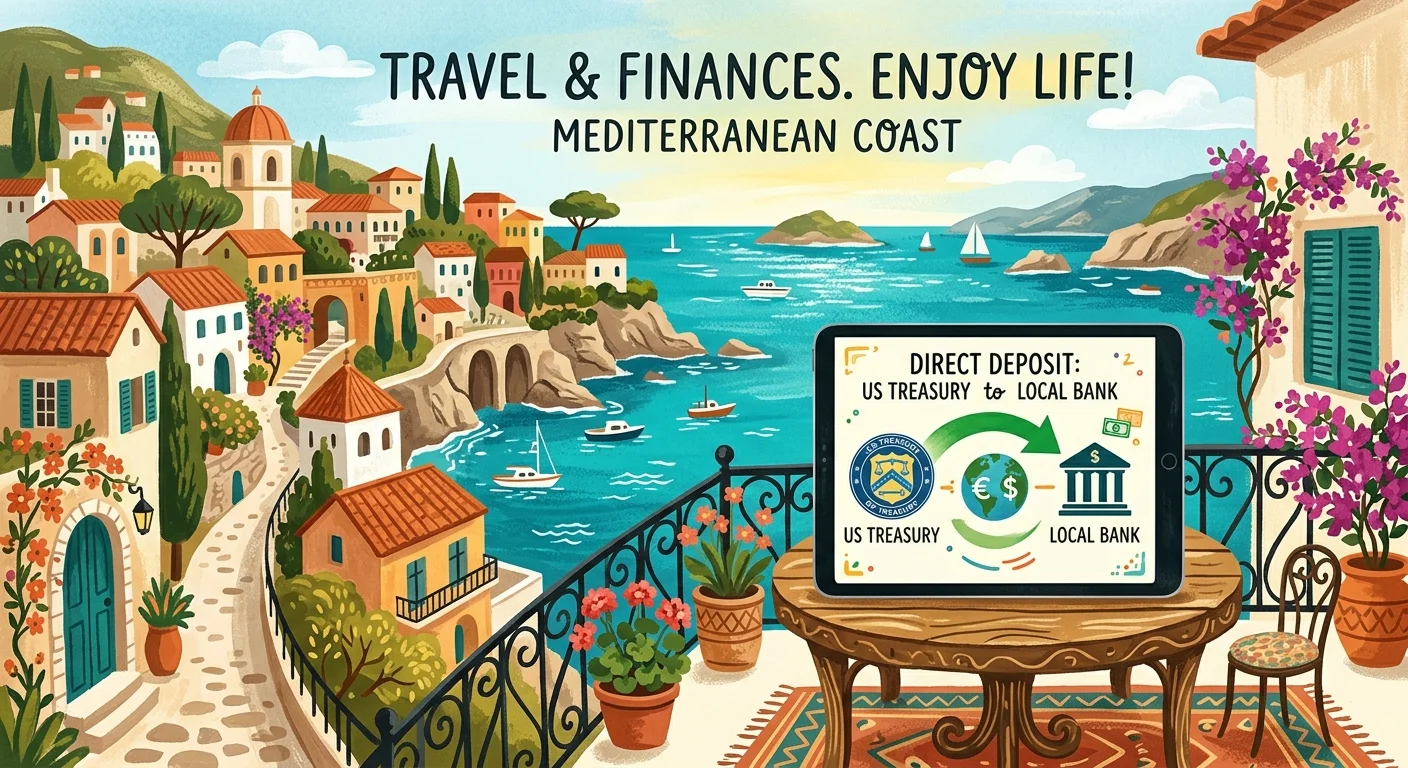
You can generally receive your full Social Security payments while living comfortably outside the United States, provided you reside in a country that maintains favorable banking and diplomatic security agreements with the federal government. The administration seamlessly deposits your funds electronically into international or domestic bank accounts. However, Medicare absolutely does not provide any medical coverage overseas. If you abandon your active Medicare Part B enrollment while living abroad and later decide to return to the United States, you will face severe, permanent late-enrollment penalties. You must carefully weigh the high cost of maintaining unused domestic health coverage against the lifestyle savings of international expatriation.
What protections shield my Social Security payments from aggressive debt collectors?
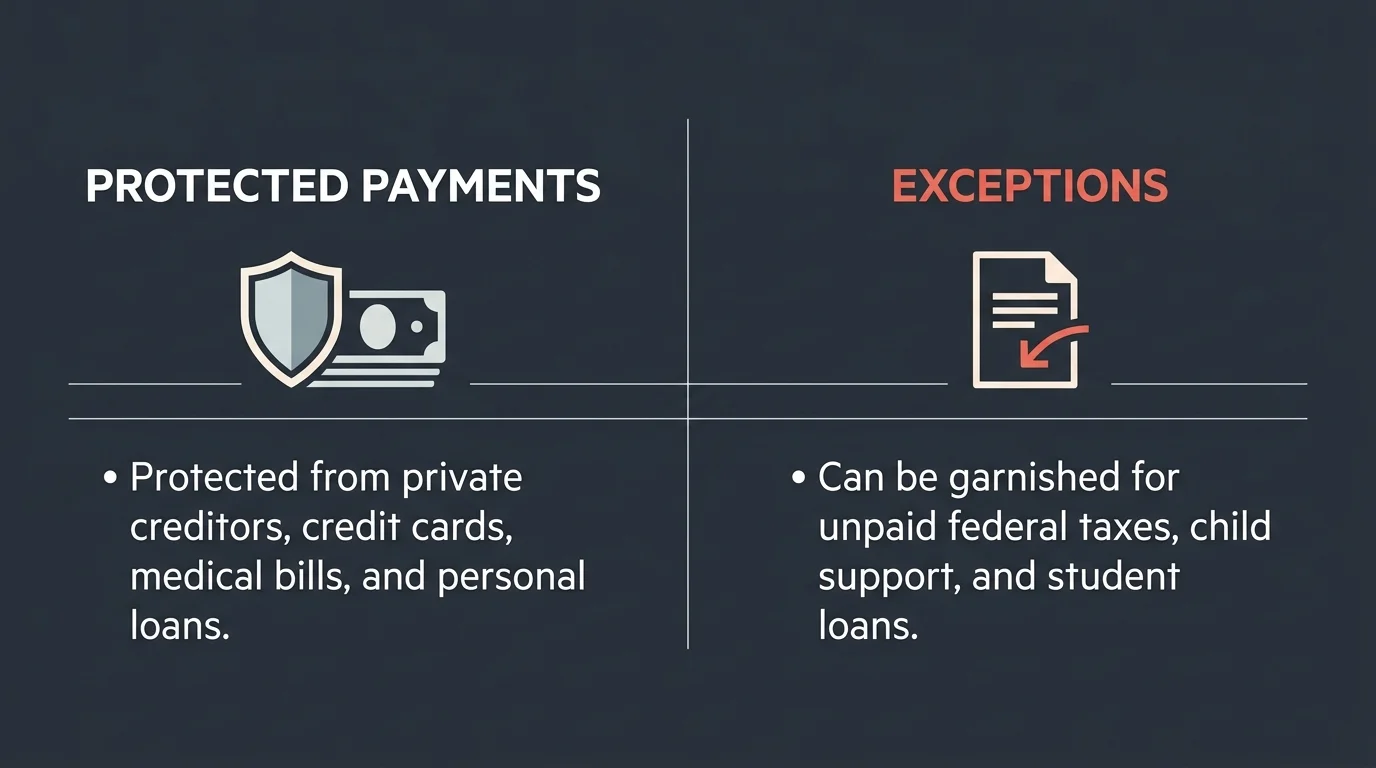
Federal law heavily fortifies your Social Security benefits against aggressive garnishment by private creditors, credit card companies, and private medical debt collectors. Even if you declare total personal bankruptcy, private creditors cannot legally seize your federal retirement income to satisfy outstanding unsecured personal debts. However, these robust protections completely vanish if you owe money directly to the government. The federal government can directly garnish your monthly check to forcibly recover unpaid income taxes, defaulted federal student loans, or delinquent child support and court-ordered alimony payments. You must properly segregate your Social Security deposits into a dedicated, unmixed bank account to clearly identify these protected funds if private debt collectors ever attempt to unlawfully freeze your assets.